
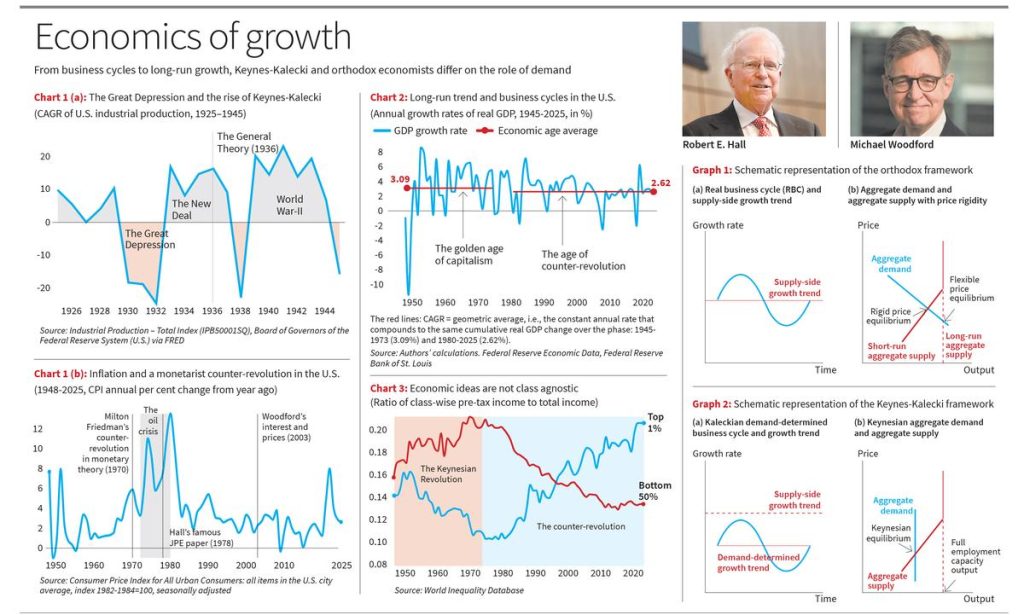
Hall and Michael Woodford have been awarded the Nobel Prize in Economics this year “for microeconomic foundations of macroeconomic stabilisation”. P rofessors Robert E. In this piece, we take a longue durée view of macroeconomics to situate their work within the context of political economy. In many ways, the field has come full circle from the days of John Maynard Keynes and Michal Kalecki (henceforth KK)
It is obvious, therefore, that policy is required only for the short run and not the long run. Because prices and wages are rigid but because capital investment by the capitalists is not enough to employ all those who seek employment, economies are stuck at below-capacity output or with unemployed workers not. The arguments and policy flowing out of the KK framework led to what is considered the golden age of capitalism (1945-1973), a period that recorded the highest sustained growth rates (compare the average growth rates across time in chart 2). This led to the development of real business cycle (RBC) theory, associated with economists Finn Kydland and Edward Prescott, who won the 2004 Nobel Prize in Economics. The economy functions along the full-employment path, with the trend determined by the growth of the labour force and its productivity (Graph 1(a)). Demand is vertical in prices (Graph 2(b)).
Ideas matter a great deal. What is a business cycle? Like a ship navigating the ocean, a capitalist economy moves through ebbs and flows in economic activity. Just as a ship cruises smoothly when the waters are calm, an economy has an underlying long-term trend rate of growth. Both the cycle and the underlying trend rate of growth have been the subject of intense debates in economics. There are two broad poles in this debate — with some variations within each: heterodox and orthodox approaches. Consider the orthodox approach. Before KK, it was believed that in the long run, economies move along full-employment paths with cycles arising from external shocks, which did not require policy interventions from the State. These arguments, however, were built on ad hoc assumptions. In the 1980s, a newer version of this orthodox approach sought to build the framework from the bottom up, moving from micro-foundations to a macroeconomic model. For them, output and labour markets clear in the short run, so even the cyclical movements were caused by the supply side, thereby precluding the possibility of any State intervention. If you consider a time period long enough (over a business cycle), on average, the prices would have adjusted fully, in which case demand also adjusts fully to what the firms would like to supply. Demand creates supply in the short run while supply determines the demand in the long run. But even more importantly, their analysis of the short term differs as well. Rigidity of investment, not prices, causes unemployment. In Keynes, prices are not even rigid, let alone being the cause of the business cycle. In Kalecki, they are, but that is not the cause of the shortage of demand. Unless the fall in prices could affect investment, it would have no impact on demand.
The role of monetary policy, therefore, was to stabilise prices. A fall in prices may in fact have a negative impact on investment through debt defaults, etc. All of this had a profound impact on both understanding the workings of a capitalist economy as well as policy prescriptions. Before Keynes, it was believed that money could not affect the ‘real’ economy, i.e., it was neutral in its impact on output. It was believed that a larger pool of money would chase the same amount of goods, which simply leads to a rise in their prices. The New Keynesian Model (NKM) agrees that this is indeed the case in the long run; however, in the short run, since prices are sticky, a rise in the money supply increases real balances in the hands of households, who increase their consumption, thereby making money non-neutral. But this holds only in the short run. the primary role of monetary policy nevertheless is to stabilise inflation While money is non-neutral in the short run. No wonder that this policy approach is called inflation targeting. The KK framework, on the other hand, did not believe that money leads to inflation. Given that the ebbs in activity were caused by a lack of adequate private investment, their policy recommendations foregrounded policies which increased the level of activity directly, i.e., through fiscal intervention by the State. If private investment is not coming through, public investment fills the gap.
