C ybercrimes have disrupted our conventional understanding of both how crimes take place and how the systems responding to them function.
the latter have captured the public’s imagination and fears in unprecedented ways While there is much to be said about the non-financial cybercrimes that may be just as prevalent as financial cybercrimes.
In financial cybercrime cases, the banking sector becomes an integral part of the reporting and resolution process, widening the traditional understanding of the core criminal justice institutions such as the police and courts. In this context, the study explores, among other things, whether banks as an institution are prepared to deal with these cases and to take accountability for security lapses. One of the first actions taken by the victim after the incident was complaining directly to the banks. A more serious allegation levelled against the banks, both by cybercrime experts as well as victims, is that of complicity in the cybercrimes, whether directly or indirectly. Overall, while a significant proportion of the victims feel that the breach of their personal data enabled the cybercrime incident, this sentiment is amplified amongst those who had first-hand experience with the bank in dealing with their case. In-depth interviews with victims made similar grave allegations against the banks. Cybercrime experts and senior police officers dealing with these cases strongly supported this perception.
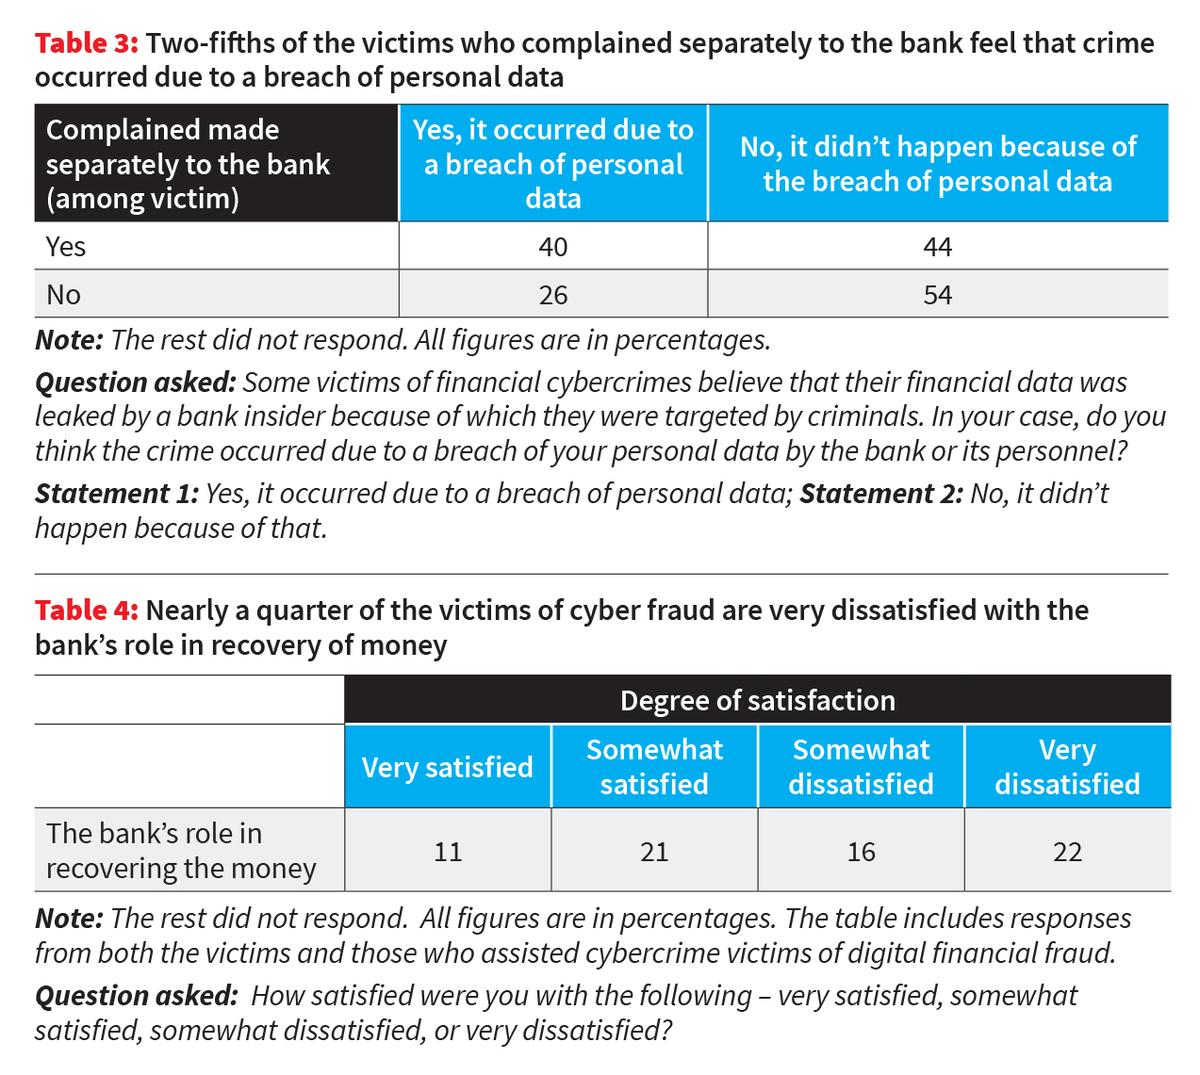
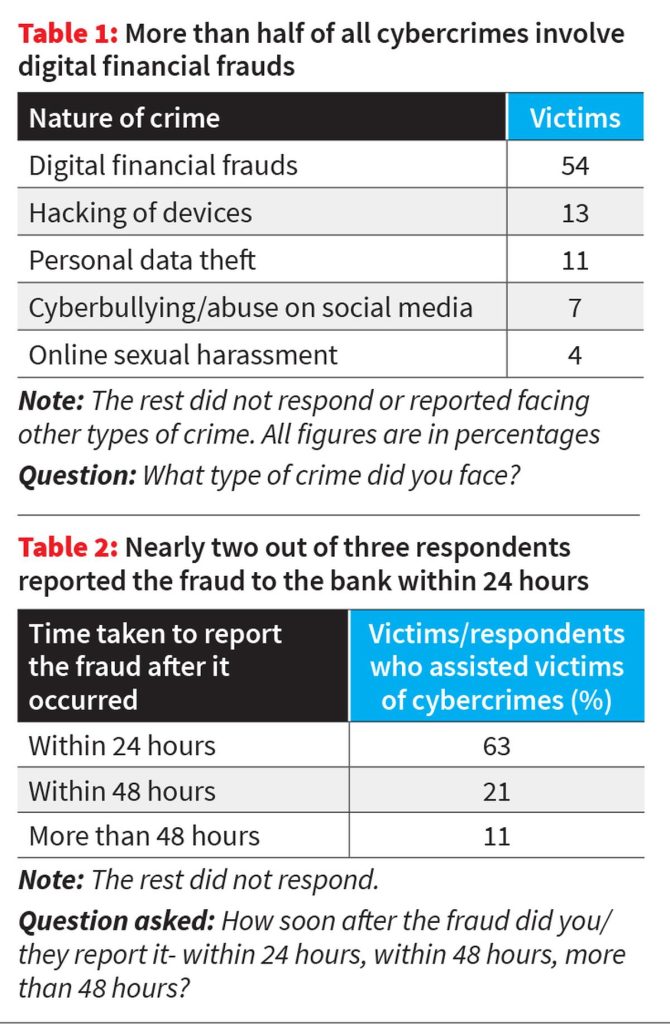
More than half of the victims of digital financial fraud (52%) who were surveyed said that they had complained to the bank separately after the incident. A majority, 63%, complained within the first 24 hours. Amongst those who did not complain to the bank separately, 26% hold this opinion. Of the 13 digital financial fraud victims interviewed, five victims were of the opinion that bank officials were directly or indirectly complicit in the crime.
The survey data shows that amongst victims who complained to the bank separately, as many as 40% were of the opinion that the cybercrime occurred due to their financial data being leaked by a bank insider. They further stressed the lack of accountability for the common leakages of customer data, due to inadequate security systems.
One of the victims was told by the police officer investigating her case that the bank must be complicit, though no charges were filed against it.
In-depth interviews with victims revealed, however, that the banks’ response to cybercrimes is almost entirely focused on evading accountability and liability. Other victims reported similar instances of delays by the banks in stopping the flow of unauthorised transactions immediately following the complaint. Notably, the one case in which the banks did not give this response included a high net-worth individual with a long-standing relationship with the bank. there is little accountability for the mental, physical and financial costs to the victim in the recovery process necessitated by such negligence While the banks become directly liable for such losses when presented with such evidence of negligence in taking prompt action.
A recent study by Common Cause and Lokniti, CSDS, the Status of Policing in India Report (SPIR) 2026: Cybercrimes — Victim Perspectives and Systemic Responses, brings out the perspectives of the common public, victims, and domain experts on this issue, focusing on how victims navigate through the complex systems. The study is based on a survey of 8,306 respondents from across 16 States/U.T.s, along with in-depth interviews with 37 stakeholders, including victims, cybercrime experts, and others.
The standard response from the banks in cases of digital financial fraud is that the victim “collaborated” with the perpetrator of the cybercrime. All the victims of digital financial cybercrimes who were interviewed qualitatively, barring one, said that the bank maintained this in their case, even in cases where the victims did not interact with the perpetrators at any point.